Introduction
Managing employee salaries involves more than transferring money into bank accounts at the end of each month. Businesses must calculate compensation correctly, understand applicable income tax deductions, maintain employee records, and fulfil their reporting responsibilities. For call centres in Pakistan, these tasks become particularly important as teams expand, employees work different shifts, and compensation includes commissions, bonuses, allowances, and performance incentives.
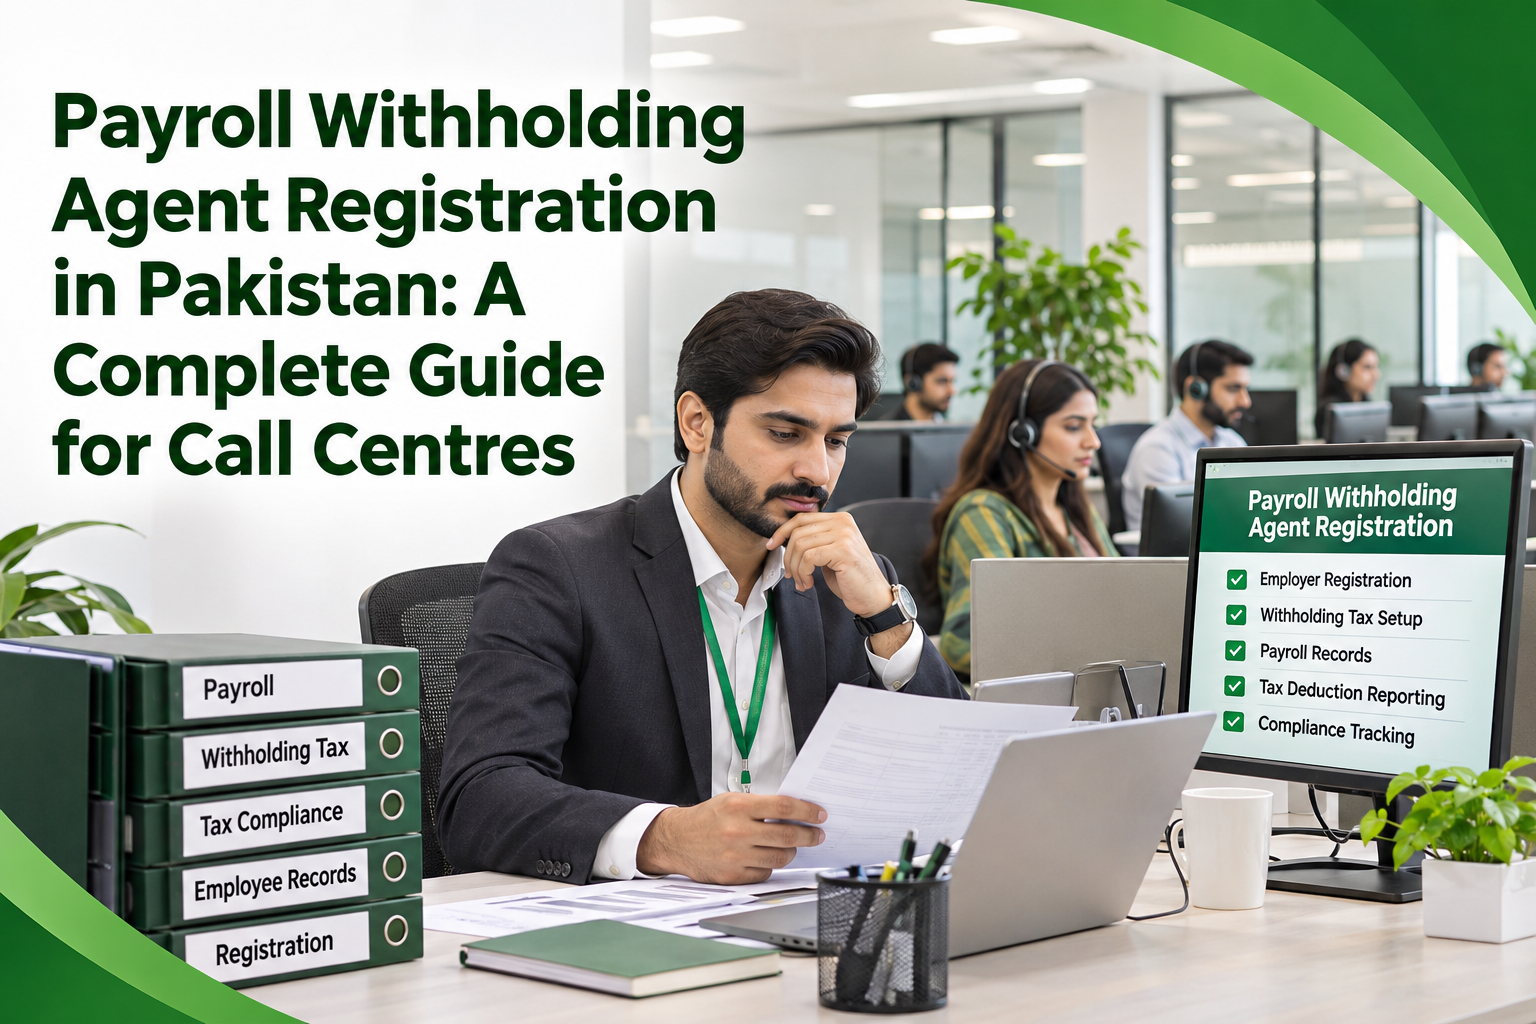
One important responsibility is understanding payroll withholding agent registration and the obligations that apply to employers under Pakistan's income tax framework. Businesses that pay salaries may have to calculate and deduct income tax where applicable and submit the relevant information to the Federal Board of Revenue (FBR). Failure to manage these responsibilities properly can create financial exposure, administrative complications, and difficulties during tax reviews.
A well-organised payroll system helps call centre owners maintain accurate records, protect employee interests, and establish a more reliable financial structure. Understanding the registration process and ongoing responsibilities is therefore an essential part of running a compliant business.
What Is Payroll Withholding Agent Registration?
Payroll withholding agent registration refers to the tax registration and administrative setup required for a business to fulfil its responsibilities as an employer that deducts and reports withholding tax on salaries.
Under Section 149 of the Income Tax Ordinance, 2001, a person responsible for paying salary to an employee is required to deduct income tax at the applicable average rate when the salary is paid, subject to the provisions of the law.
For companies operating in Pakistan, this responsibility generally forms part of their wider FBR income tax registration and reporting arrangements. It is important to understand that the term does not necessarily represent a separate standalone NTN registration for every employer. The applicable registration, IRIS access, and withholding agent responsibilities should be assessed according to the business structure and relevant tax provisions.
For a call centre, this process establishes a foundation for salary tax deduction, accurate payroll reporting, and organised tax records.
Why Call Centres Need Proper Payroll Tax Management
Call centres frequently operate with large teams, rotating shifts, performance-based compensation, and changing employee numbers. These operational characteristics make payroll administration more demanding than a straightforward monthly salary arrangement.
For example, an employee may receive a fixed salary along with sales commissions, attendance incentives, overtime payments, and additional allowances. Each payment must be recorded correctly and reviewed according to its applicable tax treatment.
Without an organised system, businesses may overlook taxable amounts, calculate deductions incorrectly, or submit inconsistent information to FBR.
Proper payroll tax compliance in Pakistan helps businesses:
-
Maintain accurate employee salary records.
-
Calculate income tax deductions according to applicable rules.
-
Reduce mistakes in monthly payroll processing.
-
Maintain reliable tax payment and reporting evidence.
-
Manage employee joining, resignation, and salary adjustments.
-
Prepare for tax assessments and regulatory reviews.
-
Improve transparency between management and employees.
For growing businesses, these practices also make financial planning more predictable.
1. Complete the Relevant FBR Income Tax Registration
The first step is establishing the correct tax registration for the business. A call centre operating as a private limited company, association of persons, or another recognised structure must ensure that its FBR registration reflects its legal identity and business information.
FBR uses the IRIS system for income tax registration and online tax administration. Once the relevant registration is completed, the business receives its applicable NTN or registration number and access credentials.
For companies and associations of persons, the registration process involves providing the required information through the relevant FBR registration channel. Businesses should prepare their incorporation or partnership documents, business address, principal officer information, and other supporting particulars.
The registration details should remain consistent with the business's legal and banking records. Incorrect company particulars, outdated contact information, or incomplete registration details can create difficulties when submitting tax information.
Businesses seeking FBR payroll registration should first review their existing tax status rather than assuming they need an entirely separate registration. They should also confirm that their IRIS profile and authorised representatives can access the relevant withholding tax functions.
2. Understand Employer Responsibilities Under Section 149
Section 149 of the Income Tax Ordinance, 2001 establishes the salary withholding responsibilities of persons responsible for making salary payments.
Employers must calculate the applicable tax using the employee's estimated taxable salary income for the relevant tax year and the prescribed rates. The calculation also takes into account relevant adjustments and documentary evidence where permitted under the law.
For call centres, this requires a reliable record of employee compensation. Payroll information should include basic salaries, applicable allowances, commissions, bonuses, and other relevant payments.
Consider a call centre employee whose monthly compensation changes because of sales incentives. Calculating deductions only from the fixed salary without reviewing the additional taxable compensation could result in an incorrect annual tax estimate.
Employers should periodically review payroll calculations to reflect salary increases, employee promotions, new allowances, and changes in individual circumstances.
A properly maintained Section 149 salary tax deduction process helps ensure that the employer meets its statutory responsibilities while employees receive more accurate salary records.
3. Prepare the Documents Required for Payroll Tax Administration
Accurate documentation makes the registration and reporting process easier. Before implementing a payroll withholding arrangement, businesses should organise their legal, financial, and employee information.
Commonly required business records include:
-
Company incorporation certificate or relevant partnership documents.
-
National Tax Number and FBR registration information.
-
Business address and contact information.
-
Bank account particulars.
-
Details of the authorised representative or principal officer.
-
Employee identification and employment information.
-
Salary structures and compensation agreements.
-
Payroll summaries and supporting accounting records.
The exact documentation depends on the business structure and the particular registration or filing being completed.
Call centres should also establish a centralised employee database. This database should record joining dates, job positions, salary changes, payment information, and employment status.
Having these documents organised reduces administrative delays and supports accurate FBR withholding tax registration and reporting.
4. Calculate Employee Salary Tax Correctly
Calculating employee income tax is one of the most important responsibilities of payroll administration.
An employer must review the applicable salary tax slabs and calculate the employee's average tax rate according to the estimated annual taxable salary. The relevant tax rates may change between tax years, so businesses should avoid relying on outdated payroll spreadsheets.
Call centres should pay particular attention to variable compensation. Sales incentives, productivity bonuses, attendance rewards, and other payments need to be reviewed under the applicable salary tax rules.
A practical payroll calculation process should include:
Basic Salary: Record the employee's contractual monthly compensation.
Allowances: Identify applicable allowances and determine their tax treatment under current legislation.
Bonuses and Incentives: Include relevant additional payments when estimating annual taxable salary.
Previous Deductions: Review tax already deducted during the tax year to avoid unnecessary over-deduction or under-deduction.
Tax Adjustments: Apply permissible adjustments and tax credits where supported by the required documentation.
A structured salary tax calculation system reduces errors and makes salary processing more transparent.
5. Manage Withholding Tax Statements Through FBR IRIS
Deducting income tax is only one part of an employer's responsibility. Businesses must also fulfil their applicable withholding tax reporting obligations.
Sections 165 and 165C of the Income Tax Ordinance, 2001 establish statement-related requirements for withholding agents, with filing periods prescribed under the applicable law and rules.
Call centres should ensure that their withholding records are accurately reflected in the relevant FBR reporting process. The information may include employee identification particulars, payments, deductions, and deposited tax amounts.
The finance department should regularly reconcile:
-
Total salaries paid during the reporting period.
-
Taxable compensation recorded in payroll.
-
Income tax deducted from employees.
-
Tax deposited with the government.
-
Information submitted through IRIS.
Any difference should be investigated before filing or correcting a statement.
An effective FBR withholding tax statement process helps businesses maintain consistency between payroll records, bank transactions, and tax submissions.
6. Separate Salary Withholding From Vendor Withholding
Another common mistake among growing call centres is treating every withholding tax responsibility as part of employee payroll.
Businesses may also make payments to internet providers, marketing agencies, software suppliers, landlords, professional consultants, and security service providers. Depending on the nature of the payment and the applicable provisions, these transactions may attract separate withholding tax obligations.
Salary deductions generally fall under Section 149, while certain payments for goods, services, and contracts may fall under other provisions, including Section 153.
These transactions should be recorded separately because the applicable rules, rates, exemptions, and reporting treatment may differ.
A complete business withholding tax compliance system should therefore cover both employee compensation and relevant supplier payments.
This separation makes reconciliation easier and prevents payroll teams from incorrectly applying salary tax procedures to commercial transactions.
7. Maintain Employee Records and Payroll Transparency
Payroll compliance also depends on the quality of employee information.
Call centres frequently recruit agents, replace employees, transfer staff between departments, and revise compensation structures. Every change should be reflected in the payroll database.
Employers should maintain employment contracts, salary revisions, attendance records, incentive calculations, approved deductions, and payment evidence.
Employee records should also be protected through appropriate access controls. Salary information and personal identification details should only be available to authorised personnel.
Providing employees with clear salary statements helps them understand their earnings and deductions. Businesses should also maintain reliable records of tax deducted and provide the relevant withholding information or certificates as required.
A transparent employee payroll management system supports better communication between HR, finance, management, and employees.
8. Avoid Common Payroll Withholding Mistakes
Many businesses do not encounter payroll compliance problems because they deliberately ignore tax requirements. More often, issues develop through manual calculations, outdated information, poor communication, and inconsistent documentation.
Some common mistakes include:
Using Outdated Tax Rates: Salary calculations should reflect the applicable tax year rather than an old spreadsheet.
Ignoring Variable Compensation: Commissions and incentives should be reviewed when calculating estimated annual salary income.
Missing Reporting Deadlines: Businesses should maintain a tax calendar and monitor the applicable filing periods.
Incorrect Employee Information: Incomplete identification and salary records can affect the accuracy of withholding statements.
Failure to Reconcile Deductions: Payroll deductions should match the corresponding tax deposits and reporting records.
Mixing Different Withholding Categories: Salary withholding and vendor withholding should be managed separately under their respective legal provisions.
Avoiding these mistakes requires clear internal responsibilities and regular reviews.
9. Create a Practical Payroll Withholding Compliance Checklist
A practical checklist allows business owners to monitor their payroll tax responsibilities throughout the year.
Before implementing payroll withholding, confirm that the business has the appropriate FBR registration and IRIS access. Review Section 149 requirements and establish a consistent method for estimating employee taxable income.
During payroll processing, update employee records, verify salary components, calculate applicable deductions, and maintain payment evidence. Review any changes involving bonuses, promotions, resignations, or revised compensation.
For tax reporting, reconcile deductions against deposited amounts, prepare the required withholding statements, and monitor filing deadlines.
At the end of the tax year, review the annual payroll summary, confirm the accuracy of deductions, and retain the supporting documentation.
This approach creates an organised payroll tax compliance checklist that can grow alongside the business.
10. How Professional Payroll Compliance Services Help
Managing payroll withholding responsibilities can become challenging when a call centre operates multiple shifts, employs a large workforce, or serves international clients.
Professional support can help businesses organise their tax registration, review payroll calculations, prepare withholding statements, and identify compliance gaps.
An experienced adviser can also coordinate payroll information with accounting records and other corporate compliance responsibilities. This reduces the burden on internal management and gives business owners a clearer understanding of their obligations.
For companies that require payroll withholding agent registration support, professional assistance can help assess the existing FBR profile, identify the appropriate setup, organise supporting documents, and manage the relevant reporting process.
Pakistan's First Online Consultants (PFOC) supports businesses through payroll management, withholding tax reporting, corporate compliance, and related advisory services. A coordinated approach allows call centre owners to focus on employees, clients, and business development while keeping administrative responsibilities organised.
Conclusion
Payroll withholding is an important part of operating a compliant call centre in Pakistan. Businesses must understand their responsibilities under the Income Tax Ordinance, maintain suitable FBR registration, calculate employee salary tax accurately, and complete the relevant withholding statements.
A reliable payroll system also needs proper documentation, regular reconciliation, and coordination between HR and finance departments. These practices reduce administrative errors and help businesses respond confidently to regulatory requirements.
The key is to establish a structured process before payroll responsibilities become difficult to manage. With appropriate tax guidance, accurate employee records, and consistent reporting, call centres can build a stronger financial foundation and support sustainable business growth.

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek