Precision Agriculture Fuels the Global Alachlor Market Toward USD 300 Million by 2034
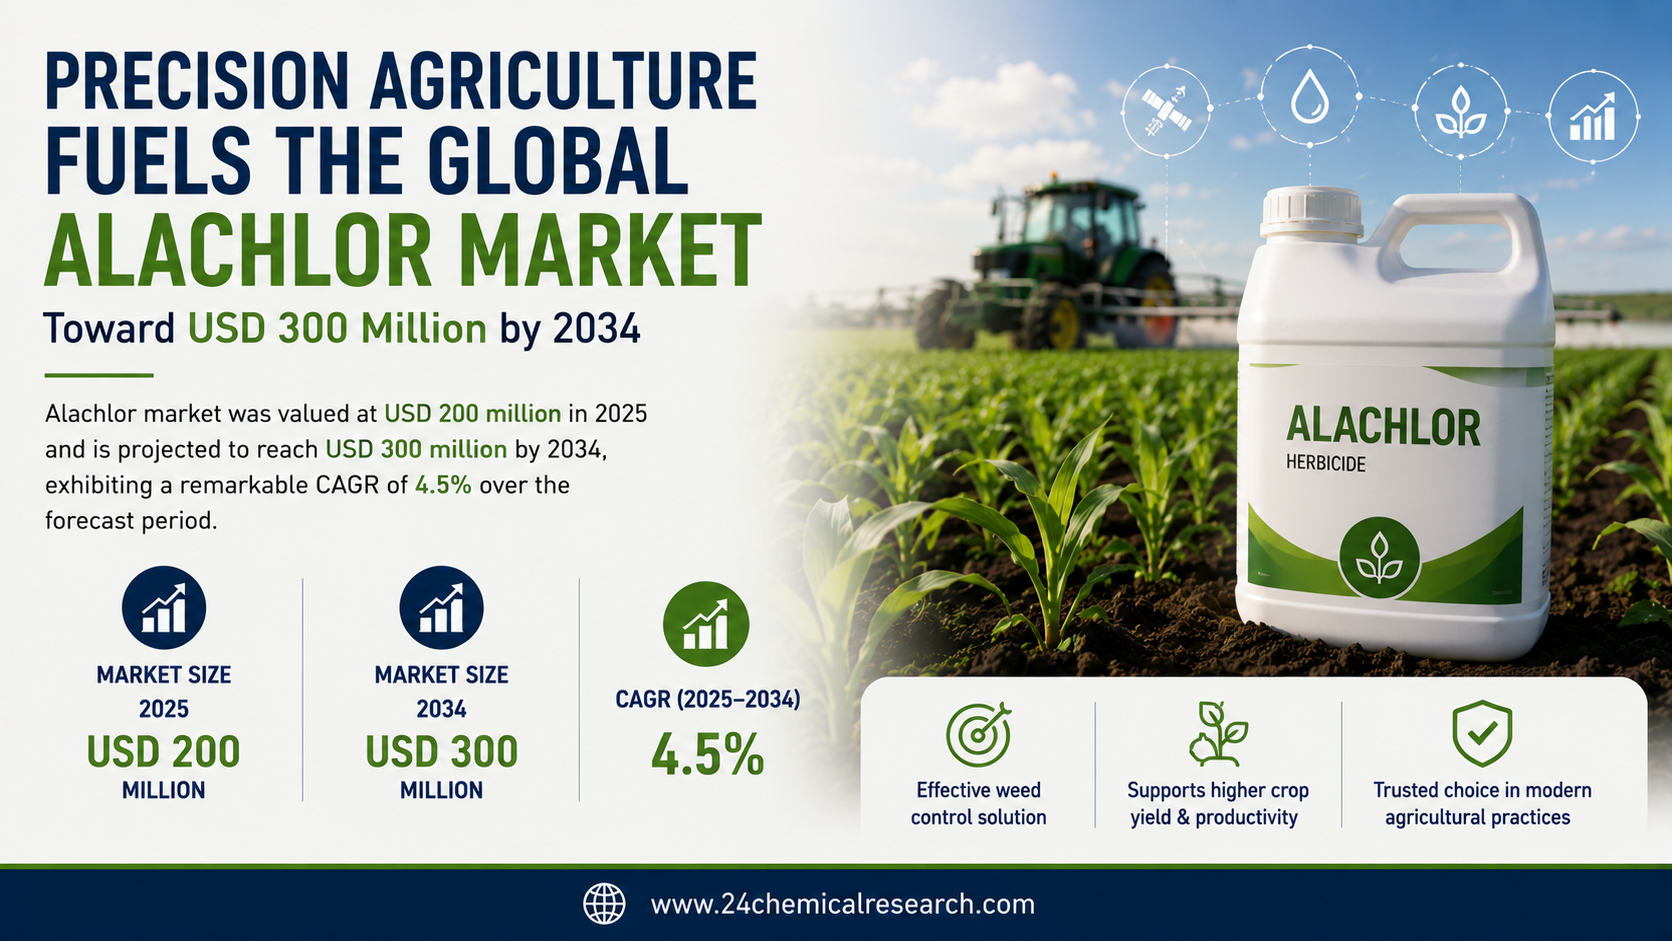
Alachlor market was valued at USD 200 million in 2025 and is projected to reach USD 300 million by 2034, exhibiting a remarkable CAGR of 4.5 % over the forecast period.
Alachlor, a pre‑emergence, broad‑spectrum herbicide belonging to the chloroacetanilide family, has become an indispensable tool in modern agriculture. Its chemical structure enables efficient control of annual grasses and a wide spectrum of broadleaf weeds that compete with major row crops such as corn, soybeans and cotton. Unlike many legacy herbicides that require multiple applications, Alachlor’s persistent activity in the soil offers a single‑application solution, reducing labor, fuel consumption and overall crop‑management costs. Over the past decade, sustained research into formulation science, seed‑treatment technologies and precision‑agriculture delivery systems has expanded the herbicide’s agronomic relevance, making it a cornerstone of integrated weed‑management programs worldwide.
Get Full Report Here: https://www.24chemicalresearch.com/reports/316881/alachlor-market
Market Dynamics:
The market’s trajectory is shaped by a complex interplay of powerful growth drivers, significant restraints that are being actively addressed, and vast, untapped opportunities.
Powerful Market Drivers Propelling Expansion
- Growing Demand for Broadleaf Weed Control: Crop producers worldwide continue to prioritize high‑efficiency herbicides that can deliver reliable control of broadleaf weeds, which are responsible for substantial yield losses in corn and soybean rotations. Alachlor’s proven efficacy against species such as pigweed, lambsquarters and sicklepod makes it a preferred choice for growers seeking to protect canopy development during the critical early growth stages. According to USDA pesticide usage reports, the acreage treated with Alachlor‑based formulations has shown a steady upward trend across the United States, Brazil and Argentina, driven by the herbicide’s cost‑effectiveness and compatibility with existing agronomic practices.
- Regulatory Acceptance in Key Regions: Several major regulatory agencies, including the U.S. Environmental Protection Agency (EPA) and Brazil’s Agência Nacional de Vigilância Sanitária (ANVISA), have reaffirmed Alachlor’s safety profile when applied according to label recommendations. This regulatory clarity has facilitated continued commercial distribution in North America, South America and parts of Asia, encouraging seed‑treatment partnerships and bulk‑sale contracts that enhance market stability.
- Precision‑Agriculture Integration: The rapid adoption of digital farming technologies-such as satellite‑guided variable‑rate application, drone‑based scouting and IoT‑enabled sprayers-has created a fertile environment for Alachlor’s targeted use. Precision tools enable growers to apply the herbicide only where weed pressure is highest, thereby improving cost‑effectiveness, reducing off‑target exposure and aligning with sustainability goals. Industry surveys indicate that farms employing precision applicators achieve up to a 12 % reduction in overall herbicide consumption while maintaining equivalent weed‑control performance.
Download FREE Sample Report: https://www.24chemicalresearch.com/download-sample/316881/alachlor-market
Significant Market Restraints Challenging Adoption
Despite its promise, the market faces hurdles that must be overcome to achieve universal adoption.
- Increasing Scrutiny on Soil Residues: Environmental watchdogs in Europe and several Pacific nations have heightened concerns about Alachlor’s persistence in soil and potential leaching into groundwater. Scientific studies published in peer‑reviewed journals have documented detectable residues beyond the typical cropping cycle, prompting some jurisdictions to impose stricter monitoring requirements and lower permissible application rates.
- Stringent Pesticide Regulations: The European Union’s regulatory framework has moved toward tighter pesticide thresholds, effectively limiting Alachlor’s use on food crops after the 2018 ban. Compliance often requires additional testing, documentation and, in some cases, reformulation, which can increase time‑to‑market and cost for manufacturers. Smaller farms, lacking the resources to navigate complex approval processes, may shift to alternative herbicides with less regulatory burden.
Critical Market Challenges Requiring Innovation
The transition from laboratory success to industrial‑scale manufacturing presents its own set of challenges. Maintaining consistent active‑ingredient purity at volumes exceeding 100 kg per day is difficult, and current processes yield only 60‑70 % usable material due to by‑product formation. Moreover, ensuring uniform dispersion of Alachlor in granular or liquid formulations is problematic; premature agglomeration can occur in 30‑40 % of batches, leading to inconsistent field performance. These technical hurdles drive substantial R&D spending-often 15‑20 % of annual revenue for leading agrochemical firms-as they strive to improve synthesis pathways, enhance formulation stability and reduce production costs.
Additionally, the market contends with an immature and fragmented supply chain. Volatility in raw‑material prices for key precursors such as 2‑chloro‑2′‑ethyl‑acetanilide can fluctuate by 15‑25 % annually, while logistics challenges associated with transporting bulk chemicals add 5‑7 % to overall production costs. These uncertainties create economic risk for large‑scale end‑users who require predictable pricing to formulate long‑term budgeting strategies.
Vast Market Opportunities on the Horizon
- Formulation Innovations for Enhanced Safety: Investors are channeling resources into micro‑encapsulation, controlled‑release granules and seed‑coating technologies that reduce drift, lower residue levels and improve soil persistence profiles. Such innovations address regulatory concerns while preserving Alachlor’s herbicidal potency, opening doors to markets that previously restricted its use due to environmental considerations.
- Expansion into Emerging Economies: Sub‑Saharan Africa and Southeast Asia present untapped acreage where broadleaf weed pressure is intensifying as smallholder farms adopt mechanised planting. Tailored packaging sizes, agronomic support services and locally‑adapted formulations can capture this growing demand, especially in regions where cost‑sensitive growers seek reliable, low‑input weed‑management solutions.
- Strategic Partnerships and Digital Platforms: A surge in collaboration between agrochemical manufacturers, seed‑technology companies and ag‑tech service providers is reshaping the value chain. By co‑developing data‑driven application protocols, firms can reduce the “valley of death” between research and commercial adoption, accelerating time‑to‑market by 30‑40 % and fostering a more resilient ecosystem for Alachlor‑based products.
In-Depth Segment Analysis: Where is the Growth Concentrated?
By Type:
The market is segmented into Pre‑emergent herbicide, Soil‑applied formulation, Granular product and Liquid concentrate. Pre‑emergent herbicide dominates the Alachlor market because it offers reliable early‑season weed control, especially in corn and soybean rotations. Agronomists favor the soil‑applied format for its consistent incorporation into the seed zone, which reduces weed emergence without impacting crop germination. Granular products are preferred in regions where precise placement is essential, whereas liquid concentrates are valued for their flexibility in tank‑mixing with other crop‑protection agents. Overall, the type‑based segmentation reflects growers’ emphasis on operational simplicity, compatibility with existing equipment, and the desire for a single‑application solution that protects the crop during its most vulnerable stages.
By Application:
Application segments include Corn production, Soybean cultivation, Cotton farming and Other row crops. Corn production stands out as the leading application segment for Alachlor, driven by the herbicide’s proven efficacy against a broad spectrum of annual grasses and broadleaf weeds that challenge corn yields. In soybean cultivation, Alachlor is valued for its residual activity that bridges the weed‑free period before the crop establishes a strong canopy. Cotton growers appreciate the product’s ability to manage early‑season weeds that compete for moisture and nutrients. Across all row crops, the common thread is the reliance on Alachlor as a dependable pre‑plant tool that integrates seamlessly into standard agronomic programs, thereby simplifying weed‑management decisions and supporting overall crop health.
By End User:
The end‑user landscape includes Commercial farmers, Co‑operatives and distributor networks, and Agricultural research institutions. Commercial farmers drive the bulk of Alachlor consumption, as they prioritize a predictable, high‑performance herbicide that fits into large‑scale planting schedules. Co‑operatives and distributor networks play a pivotal role by providing localized expertise, customized advisory services, and ensuring timely product availability, which reinforces adoption among smaller holdings. Agricultural research institutions contribute by generating field data that validates Alachlor’s agronomic benefits, influencing extension recommendations and reinforcing confidence across the value chain. Together, these end‑user groups create a dynamic ecosystem that sustains demand through trusted relationships, technical support and continuous validation of the herbicide’s operational advantages.
Competitive Landscape:
The Alachlor segment continues to be dominated by a handful of multinational agriscience groups that leverage extensive research pipelines and global distribution networks. Bayer Crop Science, headquartered in Germany, remains the de‑facto market leader thanks to a broad pre‑mix portfolio that integrates Alachlor with complementary weed‑control agents. Corteva Agriscience, operating out of the United States, has entrenched its position through aggressive acquisition of legacy Dow AgroSciences assets and a focus on high‑yield corn and soybean applications. Syngenta, based in Switzerland, differentiates its Alachlor offering by coupling it with advanced seed‑treatment technologies, allowing customers to address both pre‑ and post‑emergence weed pressures. BASF, another German heavyweight, uses its chemical manufacturing scale to keep unit costs low, a vital advantage in price‑sensitive commodity markets. Collectively, these firms command the majority of global sales, shape pricing benchmarks and influence regulatory dialogues in key regions such as North America, Europe and Brazil.
Beyond the traditional powerhouses, a wave of niche manufacturers is reshaping the competitive terrain. ADAMA Agricultural Solutions of Israel has carved out a reputation for producing cost‑effective generic formulations, appealing to growers in emerging economies where price elasticity is high. Nufarm, an Australian‑based company, focuses on grain‑focused markets in Asia‑Pacific, positioning its Alachlor blends as part of integrated pest‑management packages. FMC Corporation in the United States has revived interest in Alachlor through targeted R&D aimed at improving soil persistence while reducing leaching risk. UPL Limited from India leverages its extensive agro‑chemical service platform to offer bundled solutions that combine Alachlor with micronutrient delivery. These players, while smaller in scale, introduce competitive pressure by expanding product accessibility, tailoring regional formulations and often prompting the larger incumbents to refine their own value propositions.
List of Key Alachlor Companies Profiled
- Bayer Crop Science (Germany)
- Corteva Agriscience (United States)
- Syngenta (Switzerland)
- BASF (Germany)
- ADAMA Agricultural Solutions (Israel)
- Nufarm (Australia)
- FMC Corporation (United States)
- UPL Limited (India)
- Mitsui & Co. (Japan)
Get Full Report Here: https://www.24chemicalresearch.com/reports/316881/alachlor-market
Download FREE Sample Report: https://www.24chemicalresearch.com/download-sample/316881/alachlor-market
About 24chemicalresearch
Founded in 2015, 24chemicalresearch has rapidly established itself as a leader in chemical market intelligence, serving clients including over 30 Fortune 500 companies. We provide data-driven insights through rigorous research methodologies, addressing key industry factors such as government policy, emerging technologies, and competitive landscapes.
- Plant-level capacity tracking
- Real-time price monitoring
- Techno-economic feasibility studies
Contact: +91 9169162030
Website: https://www.24chemicalresearch.com/

 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek