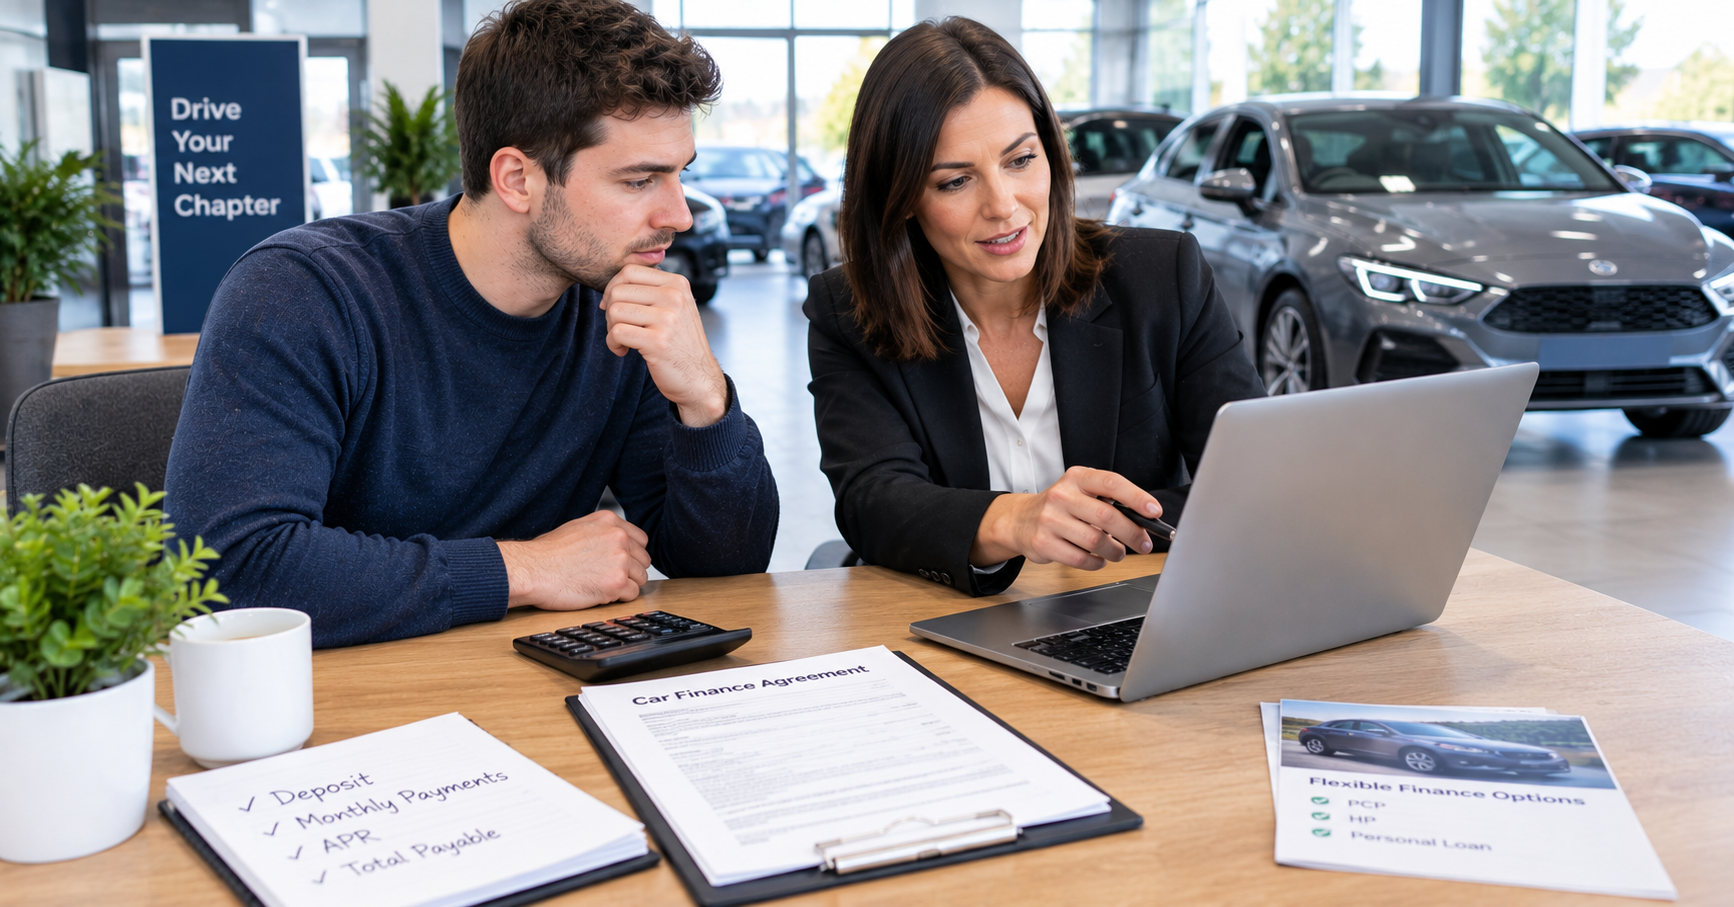
Car finance is one of the most practical ways for UK drivers to own or use a vehicle without paying the full cost upfront. Instead of a large one-time payment, you spread the cost into manageable monthly instalments, making car ownership more accessible and flexible.
Whether you're a first-time buyer or upgrading your current vehicle, understanding how car finance works in 2026 can help you avoid costly mistakes and choose the right deal. If you’re exploring reliable car financing solutions, getting the basics right from the start can save you both time and money.
What Does “Car on Finance” Mean?
A car on finance simply means you’re borrowing money to pay for a vehicle and repaying it over time with interest. Depending on the agreement, you may either:
-
Own the car at the end
-
Return it
-
Or upgrade to a newer model
This flexibility is why car finance UK continues to grow in popularity, especially among drivers looking for affordable monthly payments.
How to Get a Car on Finance (Step-by-Step Guide 2026)
-
Set your monthly budget and affordability
-
Check your credit score and eligibility
-
Choose the right car finance option
-
Compare car finance deals UK
-
Apply for car finance online or at a dealership
-
Pay deposit (if required)
-
Sign agreement and collect your car
-
Make monthly repayments responsibly
Step 1: Set Your Budget Before Choosing a Car on Finance
Before browsing cars, focus on what you can realistically afford.
Many UK buyers make the mistake of picking a car first and worrying about payments later. Instead:
-
Keep monthly payments within 15–20% of your income
-
Include running costs:
-
Insurance
-
Fuel or EV charging
-
Maintenance
-
Road tax
This approach ensures your car on finance deal remains sustainable long-term.
Step 2: Check Your Credit Score for Car Finance Approval
Your credit profile plays a major role in:
-
Approval chances
-
Interest rate (APR)
-
Monthly repayments
Why it matters:
-
Good credit → lower APR → cheaper overall cost
-
Poor credit → higher APR → more expensive deal
Quick tip:
Check your credit report before applying. Even small improvements can lead to better car finance rates in the UK.
Step 3: Choose the Right Type of Car on Finance
Understanding your options is key to making the right decision.
Hire Purchase (HP)
-
Fixed monthly payments
-
Ownership at the end
Best for: Long-term ownership
Personal Contract Purchase (PCP)
-
Lower monthly payments
-
Flexible end options
Best for: Lower monthly costs and upgrades
Personal Loan for Car Finance
-
Borrow from bank
-
Own car immediately
Best for: Strong credit holders
Leasing (PCH)
-
Monthly rental
-
No ownership
Best for: Driving new cars regularly
Best Car Finance Option in the UK (Quick Comparison)
-
HP: Best for ownership
-
PCP: Best for flexibility
-
Loan: Best for full control
-
Lease: Best for low commitment
Step 4: Understand the True Cost of a Car on Finance
A common mistake is focusing only on monthly payments.
Instead, consider:
-
APR (Annual Percentage Rate)
-
Total repayment amount
-
Loan duration
Example:
-
£220/month for 5 years = £13,200
-
£300/month for 3 years = £10,800
The second option saves money overall.
This is why comparing total cost of car finance, not just monthly payments, is essential.
Step 5: Compare Car Finance Deals UK
Never accept the first offer.
Compare:
-
Dealership finance
-
Online lenders
-
Bank loans
Look for:
-
Competitive APR
-
Flexible repayment terms
-
No hidden fees
Smart comparison can significantly reduce your car finance cost in the UK.
Step 6: Apply for a Car on Finance
The application process is straightforward.
You’ll need:
-
Proof of ID
-
Address history
-
Employment details
-
Income information
Lenders will:
-
Conduct a credit check
-
Assess affordability
Approval can be instant or take a few hours depending on the lender.
Step 7: Pay Deposit and Drive Away
Most car finance UK deals require a deposit (around 10%).
After approval:
-
Review agreement carefully
-
Sign documents
-
Collect your car
Some offers include no deposit car finance, but expect higher monthly payments.
Step 8: Avoid Common Car Finance Mistakes
1. Focusing Only on Monthly Payments
Always check the total repayment cost.
2. Ignoring Mileage Limits (PCP)
Exceeding limits leads to extra charges.
3. Not Reading Terms & Conditions
Watch for:
-
Early exit fees
-
Hidden charges
4. Overstretching Your Budget
Just because you’re approved doesn’t mean it’s affordable.
5. Skipping Deal Comparisons
You could miss better car finance deals in the UK.
Real-Life Scenarios: Choosing the Right Car on Finance
First-Time Buyer
Go for HP or small loan
Simple and predictable
Family Driver
Choose PCP
Lower monthly payments
Low Credit Score
Look for:
-
Specialist lenders
-
Higher deposit options
Frequent Upgrader
Choose PCP or leasing
Easy upgrades
Where to Find the Best Car on Finance Deals
Choosing the right provider is just as important as choosing the car.
Look for:
-
Transparent pricing
-
Flexible options
-
Trusted dealerships
Professional providers offering car financing solutions can help match you with deals suited to your financial situation, ensuring a smoother buying experience.
Is Getting a Car on Finance Worth It in 2026?
A car on finance is a smart choice if:
-
You want manageable monthly payments
-
You need a car without large upfront cost
-
You prefer financial flexibility
It may not be ideal if:
-
You want to avoid interest
-
You can afford to pay upfront
Is Car Finance a Good Idea?
Car finance is a good option if you need flexibility and choose a deal with low APR and manageable repayments. It’s less suitable if you want to avoid long-term financial commitments.
FAQs About Car on Finance UK (2026)
1. Can I get a car on finance with bad credit?
Yes, many lenders offer bad credit car finance in the UK, but interest rates may be higher.
2. What credit score is needed for car finance?
There’s no fixed requirement. Higher scores get better deals, but average scores can still qualify.
3. Is PCP better than HP?
-
PCP = lower payments
-
HP = ownership
Choose based on your priorities.
4. Can I pay off car finance early?
Yes, but early settlement fees may apply.
5. Do I need a deposit for car finance?
Usually yes, but no deposit car finance UK options are available.
6. What happens if I miss payments?
You may face:
-
Penalties
-
Credit score damage
-
Vehicle repossession
7. Is financing a used car cheaper?
Yes, used cars typically result in lower total borrowing, even if interest rates are slightly higher.
Final Thoughts
Getting a car on finance in 2026 doesn’t have to be complicated. With the right approach, it can be a smart and manageable way to drive the car you need without financial stress.
The key is simple:
-
Know your budget
-
Compare finance options
-
Focus on total cost
-
Avoid common mistakes
Take your time, explore your options, and choose a deal that genuinely fits your lifestyle. Done right, a car on finance isn’t just convenient, it’s a financially smart decision that keeps you in control.

 English
 Arabic
 French
 Spanish
 Portuguese
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek